

Growth on the Go
Drive-thru coffee is having a moment. Since 2019, the format has captured a growing share of overall coffee visits, spearheaded by pioneers like Dutch Bros. But the boom extends well beyond the category’s biggest names, with a growing crop of challengers capturing market share.
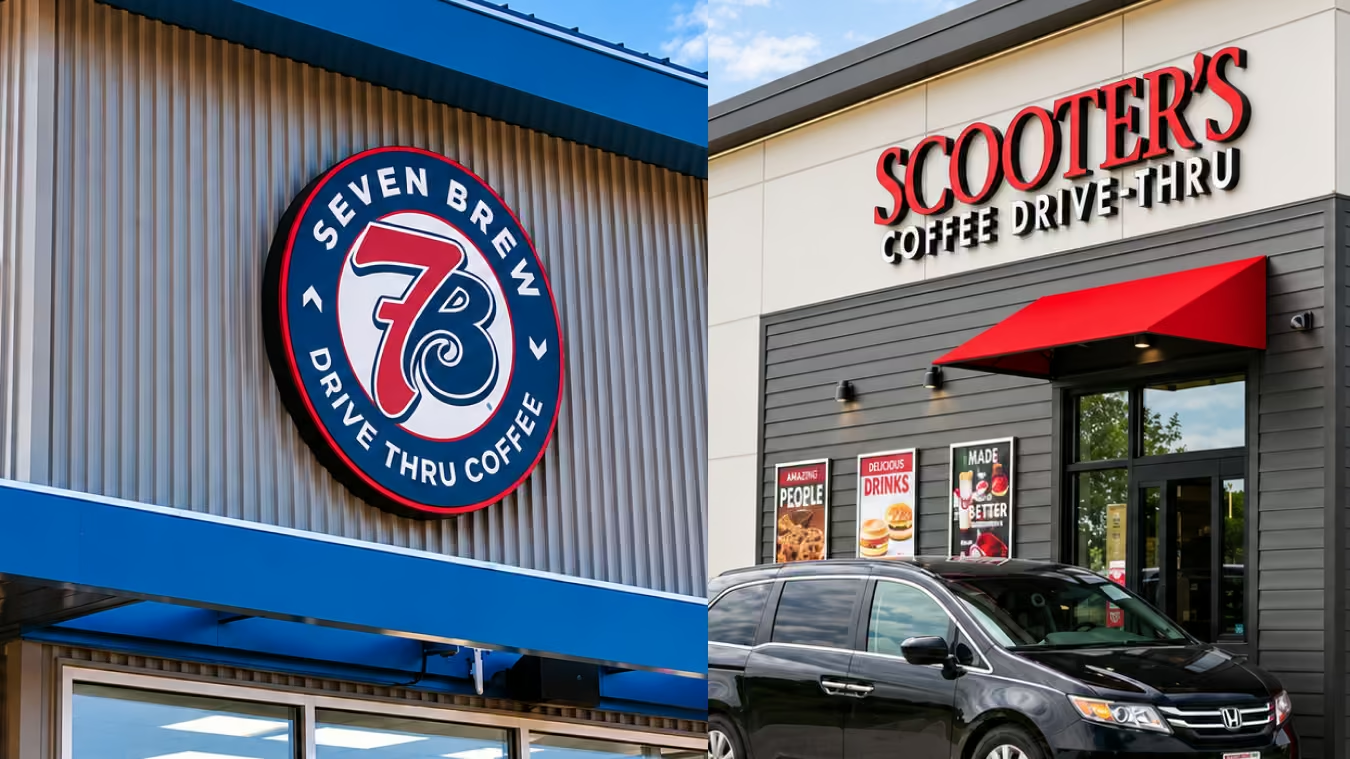
We dove into the data for two of the segment's fastest-growing smaller brands, 7 Brew and Scooter's Coffee, to see what's driving their growth – and how each chain is carving out a distinct position despite their similar footprints and customer bases.
Same Lane, Different Speeds
Both 7 Brew and Scooter's are growing in 2026, though at very different speeds. Between January and August 2026, visits to 7 Brew jumped 41.6% year over year (YoY) – a reflection of its breakneck expansion – compared with a still-healthy 6.1% increase for Scooter's, which also added stores.
But expansion isn’t the whole story. Average visits per location increased YoY at both chains, climbing 1.7% at 7 Brew and 3.7% at Scooter’s. In other words, existing stores are also attracting more customers. And although Scooter’s aggregate visit growth is far more modest than 7 Brew’s, its stronger increase in visits per location points to robust momentum within its existing store base.
Similar Footprints, Similar Audiences
The two chains share several important characteristics, including similar footprints. 7 Brew now has more than 800 stands across 38 states, while Scooter’s boasts more than 920 locations across 32 states. Their footprints overlap in roughly 30 states, putting them head-to-head in many of the same markets.
The similarities between the two brands also extend to their customers. Median household income in both chains' captured markets hovered near $75k during the analyzed period, below the nationwide benchmark of $87.3K. Both brands also over-index for one-person households and sit just above the national average for households with children.
Scooter's Owns the Morning, 7 Brew Takes the Afternoon
Hourly visit data, however, reveals an important difference between the two brands. Scooter’s is more firmly rooted in the breakfast occasion, drawing a substantially larger share of its visits in the morning. Its pastries, breakfast foods, and espresso and cold-brew lineup make it a natural first stop of the day, while a growing roster of Red Bull Infusions, sodas, and shakes gives customers more reasons to stop by later on.
After noon, the pattern flips. 7 Brew sees a larger share of its traffic between noon and 4 PM and again between 4 PM and 8 PM. That fits a concept that is beverage-forward by design. Alongside coffee, 7 Brew's menu prominently features its proprietary 7 Energy drinks, flavored sodas, teas, lemonades, smoothies, and shakes, making the chain a natural fit for an afternoon energy boost or an evening treat.
More Than One Playbook
7 Brew and Scooter’s show that there’s no single formula for succeeding in drive-thru coffee. Even with similar footprints and customer bases, the chains are building momentum around different occasions – Scooter’s with a stronger morning business, and 7 Brew with broader appeal later in the day.
For more data-driven retail analyses, follow placer.ai/anchor.
A New Chapter for Bookstore Growth
Bookstores are back. After years of doomsday predictions, chains and independents are expanding again, while niche concepts are building communities around everything from romance to horror. More than 400 independent bookstores opened in the U.S. in 2025, and Barnes & Noble added more than 60 stores, with another 60-plus slated for 2026.
So with students back on campus and fall reading lists filling up, we dove into the data to identify the nation’s five fastest-growing bookstore markets.
Atlanta Tops the Reading List
Atlanta emerged as the clear winner, with metro-wide bookstore visits up 17.4% between January and August 2026 compared with the same period in 2025. Philadelphia followed at 15.6%, ahead of Houston at 13.3%, Phoenix at 11.9%, and Chicago at 11.3%.
The five markets span four regions, suggesting that the bookstore revival is far from a one-city – or one-region – story.
Every Metro Has Its Own Plot
The drivers of that growth, however, vary by market.
In Atlanta and Houston – and, to a lesser extent, Phoenix – overall visits rose significantly faster than average visits per location, suggesting that much of the growth is being fueled by expansion. All three ranked among the fastest-growing major U.S. metros between 2024 and 2025, creating fertile ground for new bookstore openings. And each has added new Barnes & Noble locations alongside independent booksellers since mid-2025 – from a wave of new Atlanta concepts to Houston's growing roster of indie shops and a run of new indie stores across the Phoenix area.
Philadelphia and Chicago, on the other hand, showed a narrower gap between overall and per-location traffic growth, suggesting that busier existing stores are doing much of the work – even as Chicago has seen the addition of new Barnes & Noble locations this year. Some of that momentum may reflect the strength of the cities’ independent bookselling scenes, showcased by two of the country’s largest – and growing – bookstore crawls.
However You Read It
From population and footprint growth in Atlanta, Houston, and Phoenix to thriving bookstore ecosystems in Philadelphia and Chicago, the Placer Top 5 shows that there is more than one way to build a booming book market.
For more data-driven retail analyses, follow placer.ai/anchor.
A Cooler Close to Summer
After a July marked by retail growth and signs of improvement in dining, August brought a softer month for both. Retail visits saw just a slight year-over-year (YoY) uptick, while dining traffic slipped further.
We analyzed the data to understand what changed in August and which markets held up best.
Retail Flattens, Dining Slips Back
Overall brick-and-mortar retail rose just 0.3% YoY in August 2026, easing from 1.7% growth in July. Dining visits, meanwhile, fell 2.4%, reversing the gradual improvement seen in June and July.
August’s relative YoY weakness is partly a calendar effect. Labor Day fell on September 1st in 2025, putting the first part of the holiday weekend – a peak period for shopping trips and dining out – in August. This year, on the other hand, Labor Day fell on September 7th, shifting the entire holiday weekend into September. The month also traded a Friday for a Monday compared with August 2025, a calendar difference likely to have weighed more heavily on restaurant traffic than on retail.
Macro conditions, of course, were also part of the story. The national average gas price stayed above $4 per gallon throughout August, putting 2026 on track for the most expensive August at the pump on record. Consumer sentiment fell from July, while the August CPI report showed food-away-from-home prices rising 3.4% YoY, compared with 2.2% for groceries – a gap that continues to favor eating at home.
Retail Finds Regional Bright Spots as Dining Slips Nationwide
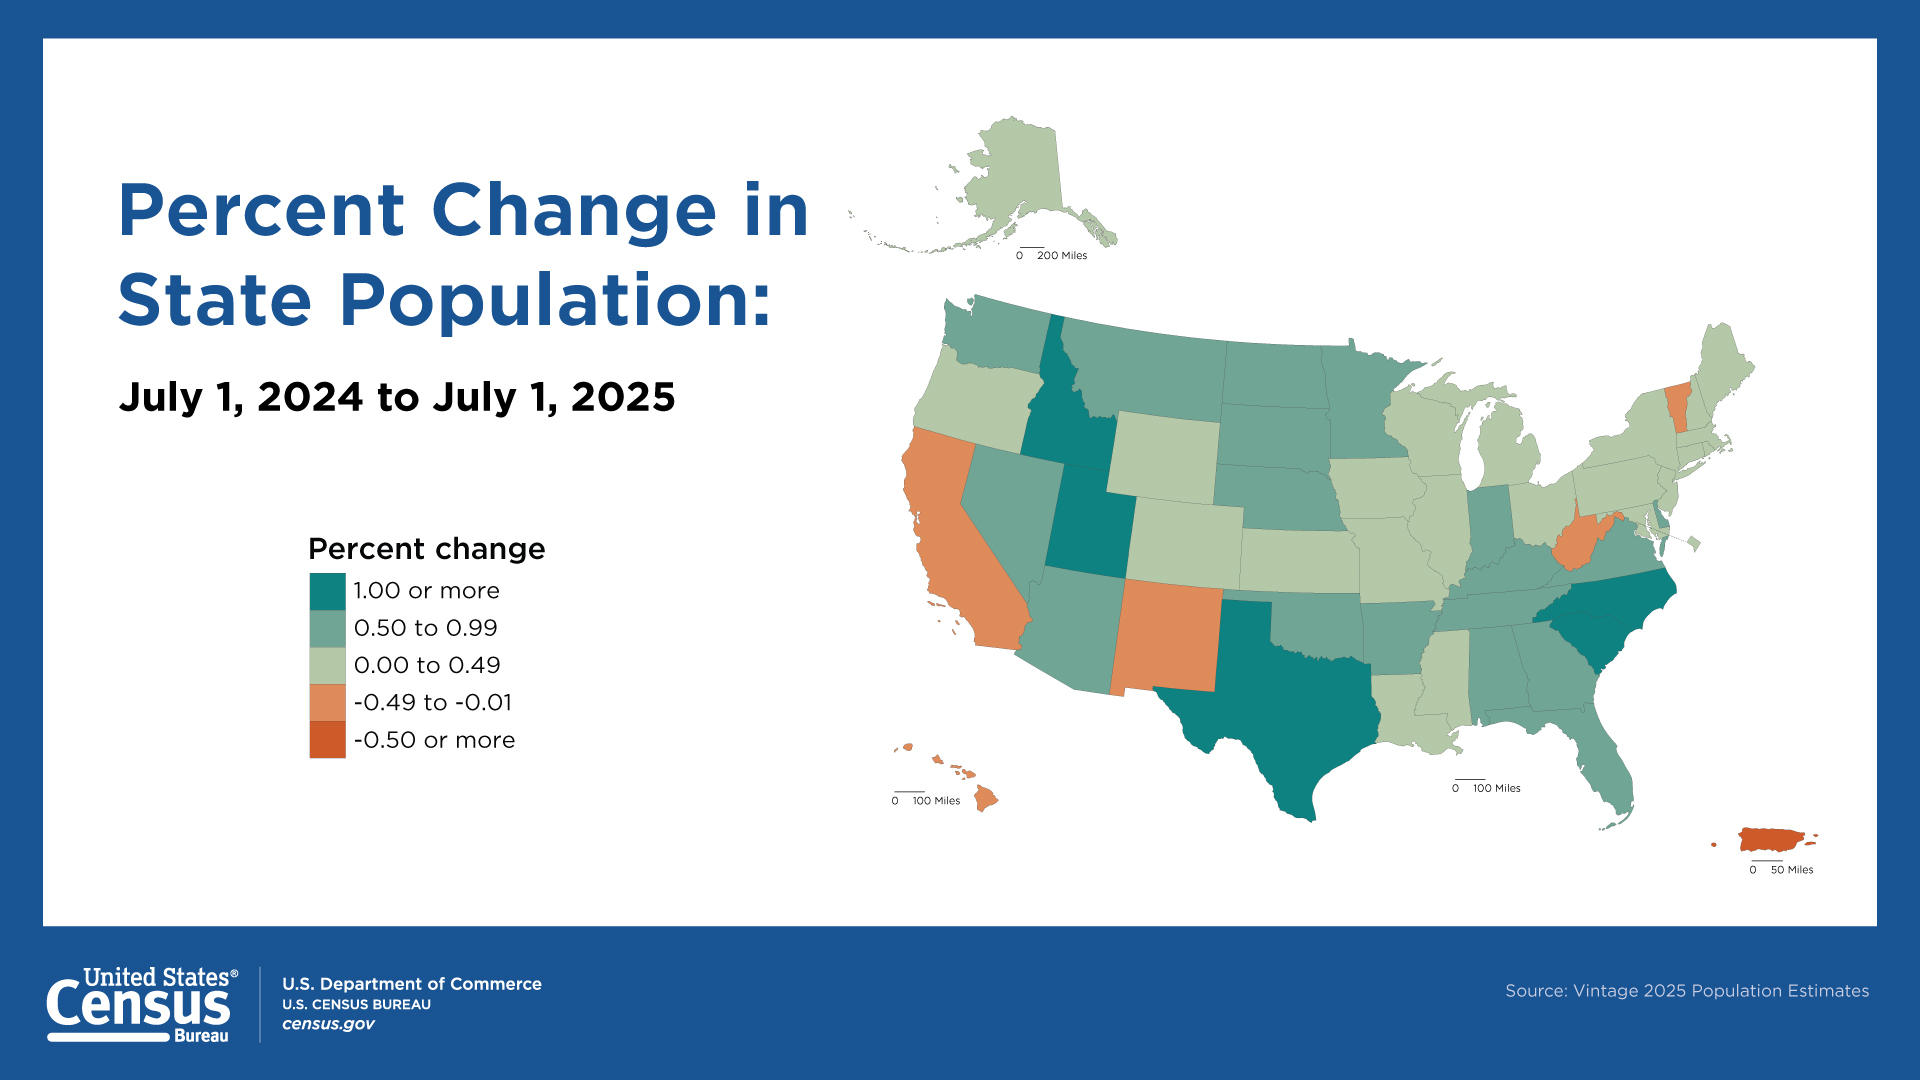
And the state-level data shows an even wider gap between the two categories. Retail was a patchwork: visits grew across much of the West – led by Utah, which continues to benefit from some of the fastest population growth in the country – as well as in Texas, Louisiana, and Georgia, while declining across much of the Plains, Ohio Valley, and Northeast.
As in July, these regional differences appear to at least partly track regional inflation trends: Consumer prices in the Northeast rose 3.9% YoY in August, compared with 3.6% in the Midwest, 3.1% in the South, and 3.2% in the West. And a stretch of heavy rain and severe storms across the Northeast and Great Lakes in late August may also have added to the pressure. Still, even the strongest retail market (Utah) posted growth of just 2.3% YoY, a reminder that August was a modest month even where conditions were relatively favorable.
Dining, on the other hand, had no such pockets of strength. Visits fell in nearly every state, and even California, the best-performing market, saw just a 0.3% YoY uptick.
Looking Ahead
August was a step back for both retail and dining, though some of that reflects a calendar shift. And with the holidays right around the corner, the question is whether dining can recover the ground it gave up – and whether retail can hold on to the growth it posted for most of 2026.

Mandates Meet the Summer Slowdown
August is typically one of the office calendar’s quieter months, as vacations and school breaks thin out workplace traffic. But this year, that seasonal slowdown coincided with a growing wave of return-to-office mandates.
So how did office traffic hold up – and what does it reveal about the state of the RTO recovery? We dove into the data to find out.
A Record August
Year over year, nationwide office visits rose 6.2% in August 2026, while remaining 32.5% below August 2019 levels – the smallest August gap since 2020.
The narrowing gap vs. 2019 is especially notable because August 2026 had just 21 working days, compared with 22 in August 2019 – giving this year one fewer day to accumulate office visits. (August 2025 also had 21 working days, while August 2024 had 22 and August 2022 and 2023 had 23.)
Miami, New York, and Dallas Stay Out Front
Miami (-11.6%), New York (-18.0%), and Dallas (-20.8%) once again led the major markets in their recovery relative to 2019, with Atlanta (-29.4%) the only other market ahead of the nationwide average.
New York also posted the strongest YoY growth, at 8.9%, rebounding from a July marked by heat emergencies, followed closely by Boston (+8.7%) and Miami (+8.6%). Los Angeles, San Francisco, and Chicago also outpaced nationwide YoY growth, even as each remained roughly 40% or more below its 2019 baseline.
At the other end of the spectrum, Washington, D.C. (-0.8%) and Denver (-3.4%) were the only markets to slip YoY, and both remain furthest from their 2019 baselines. D.C.’s weakness likely reflects a regional job market that shed more than 100,000 jobs over the past year, while Denver continues to contend with a remote-friendly work culture and record downtown vacancy.
The Autumn Test
August’s results suggest the latest wave of RTO mandates is continuing to support office traffic, even during one of the calendar’s quieter months. And with additional policies still to come, the fall will be the recovery’s next major test.
Will tighter attendance requirements push offices closer to pre-pandemic levels? And will Denver begin to see a San Francisco-like turnaround as high vacancy creates new opportunities for reinvestment?
For more data-driven office analyses, follow placer.ai/anchor.

Resilience Under Pressure
August put mall traffic to the test, with rising gas prices and softer consumer sentiment coming just as back-to-school shopping was in full swing. Against that backdrop, strength at open-air and indoor malls pointed to a resilient consumer – though the month opened a wider gap between shopping destinations close to home and outlet centers that depend on a longer drive.
Open-Air Leads as Indoor Malls Gain Ground
Open-air shopping centers sustained their lead in August 2026, with visits up 6.6% year over year (YoY). The format has posted positive YoY growth every month this year, reflecting the broad appeal of a segment that spans grocery-anchored neighborhood centers, mixed-use destinations, and experience-oriented lifestyle centers.
Indoor malls came in close behind at 5.0% – the format's largest YoY gain of 2026 – likely driven in part by back-to-school shopping. The National Retail Federation forecast a record $43.3 billion in K-12 spending this year, and with department and clothing stores ranking among the top planned shopping destinations, indoor malls were well positioned to capture that demand.
Outlet malls, meanwhile, saw visits fall 2.7% YoY, their weakest performance since March. As more distant destinations, outlet malls were likely more susceptible to higher gas prices, which ticked up on average in August after easing in June and July. And outlets may have been particularly affected by the Labor Day calendar shift: In 2025, part of the holiday weekend fell in August, while this year the entire weekend moved into September, removing a key travel and promotional period from the month’s traffic comparison.
Engagement Up Across Formats
All three formats, however, saw longer average dwell times in August than a year earlier – extending an uptick in visitor engagement that began to emerge in July after several months of declining YoY visit duration. Indoor malls and open-air centers paired those longer visits with traffic growth, while outlet malls saw the more notable combination of fewer visits and longer dwell times.
Longer dwell times may reflect a growing share of shopping center space devoted to events, attractions, dining, and placemaking, giving visitors more reasons to linger beyond shopping alone. Shoppers may also be consolidating trips as fuel costs rise, spending more time browsing and making a fuller outing of each visit.
Watching the Pump Into the Holidays
August data points to a resilient mall shopper, with visits rising at open-air and indoor centers and dwell times increasing across all three formats. Whether that resilience carries into the holidays may depend in part on what happens at the pump – though malls are entering the fall with plenty of reasons for optimism.
For more data-driven retail insights, visit placer.ai/anchor.
Five Straight Quarters of Visit Growth
Kroger has spent the past year sharpening its value proposition and optimizing its store fleet. And location intelligence data suggests the strategy is keeping shoppers coming through the doors.
Overall visits across Kroger's portfolio of banners increased 0.5% year over year (YoY) in Q2 2026, marking the grocery giant's fifth consecutive quarter of positive YoY visit growth. While this represented a moderation from the previous two quarters, it came against a strong Q2 2025 comparison, when visits rose 1.7% YoY. And notably, the overall traffic increase came even as Kroger continued to rationalize its fleet, with average visits per location rising an even stronger 1.6% YoY.
The gains come amid a broader value push by Kroger, including price cuts on more than 3,500 products since the start of 2025 and continued growth from the company’s Our Brands private label. They also align with Kroger’s recent financial performance, which saw identical sales excluding fuel rise 1.0% YoY.
Same-Store Strength Across the Portfolio
A closer look at Kroger’s five largest banners – Kroger, Fred Meyer, Harris Teeter, Ralphs, and Smith’s – shows that the Q2 strength was broad-based across the portfolio. All five posted positive same-store visit growth during the quarter, even as overall visits edged down at Harris Teeter and Fred Meyer amid store closures.
And a month-by-month view shows that the broad-based Q2 strength carried into July, when same-store visit growth accelerated across much of the portfolio. Though August brought a slight softening, this may say more about the broader macroeconomic environment than about Kroger’s own trajectory, coming as consumer sentiment declined following two consecutive months of improvement. Three of the five leading banners still posted positive same-store visit growth, led by Ralphs at 2.6% YoY.
A Leaner Fleet, A Steady Shopper Base
Kroger enters the back half of 2026 with a tighter fleet and steady momentum. With same-store visits positive across its five largest banners in Q2 and a $1.65 billion agreement to acquire Giant Eagle's nearly 200 supermarkets on the horizon, the company appears well positioned to keep winning grocery trips in the second half of 2026 and beyond.
For more data-driven retail insights, visit Placer.ai/anchor.