




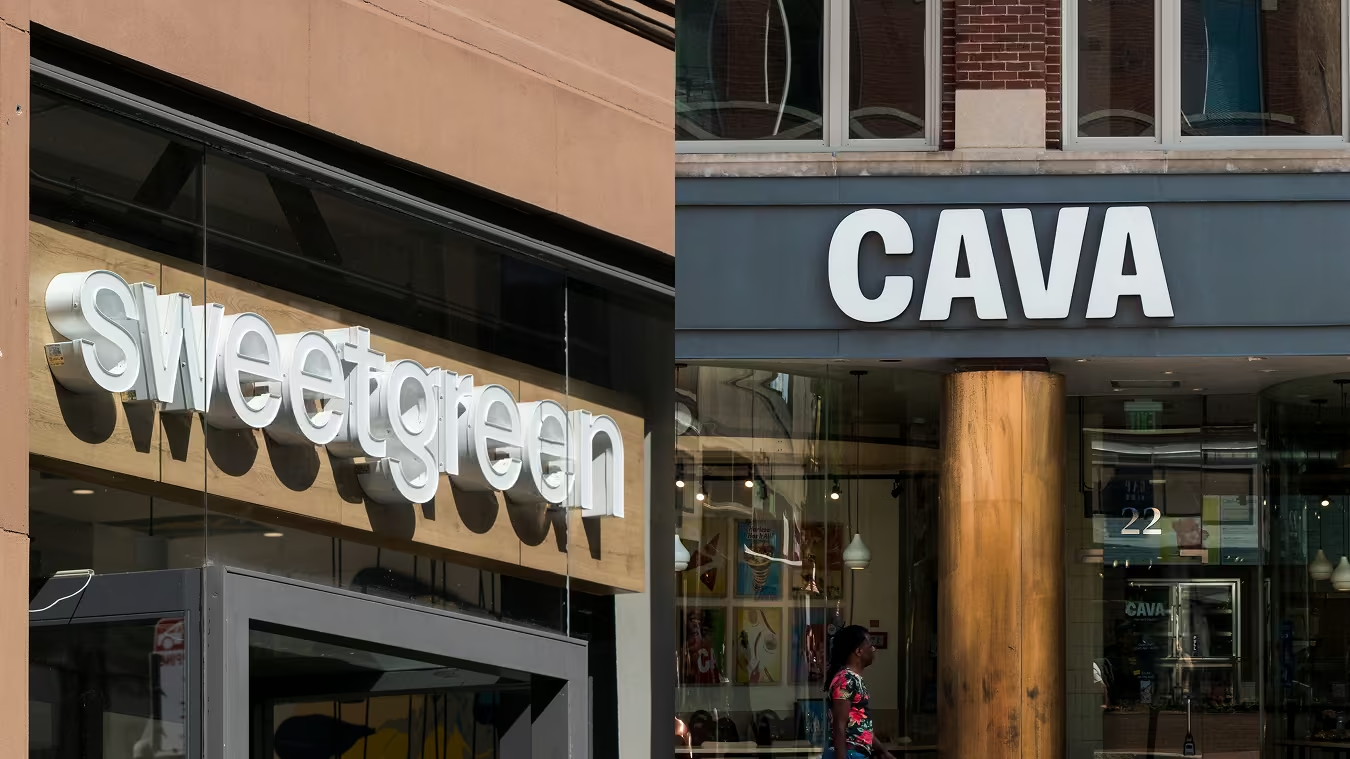
The fast casual space has become an increasingly competitive battleground for share-of-stomach as price-sensitive consumers trade down to lower-cost food channels. Against this backdrop, CAVA and sweetgreen offer a timely case study in resilience. Both brands continue to expand their footprints and diversify their audiences while leaning on loyalty programs and menu innovation to sustain growth during a volatile period for the dining sector. Using AI-powered location analytics, we uncover how macroeconomic pressures have shaped foot traffic trends to both chains and explore the strategies helping to keep them on a positive growth trajectory.
Expansion and Engagement Lift Visits
CAVA and sweetgreen continue to pursue aggressive expansion strategies, contributing to the overall visit growth of both brands. But while CAVA showed relative stability in both overall visits and same-store performance in H2 2025, sweetgreen experienced softer year-over-year (YoY) visit growth and moderate same-store visit declines in most months – raising the possibility of emerging “bowl fatigue.”
In Q4 2025, CAVA posted 16.6% YoY visit growth, with loyalty program enhancements and a holiday campaign likely helping to sustain visits.
Sweetgreen’s 4.4% visit growth in Q4 2025 was moderate by comparison, although December stood out for delivering positive YoY visits and same-store visits. This boost may have been driven by the value-focused $10 Harvest Bowl promotion alongside continued adoption of the brand’s refreshed loyalty program.
For both chains, revamped loyalty programs and continued expansion may set the stage for growth in the year ahead.
Younger Diners Show Signs of Returning as Audiences Broaden
Even as refreshed loyalty programs and expansion act as growth levers, both chains have recently called out a shared headwind – softer engagement among Gen Z and Millennial diners amid sustained financial pressure on younger consumers.
However, AI-powered captured market analysis combined with the Spatial.ai: PersonaLive dataset suggests early signs of renewed momentum. In Q4 2025, both chains saw an increased share of visitors from the “Young Urban Singles” segment – a cohort that skews heavily Gen Z and Millennial – compared to Q4 2024. And sweetgreen saw growth in its “Educated Urbanites” segment – another cohort that skews heavily Gen Z and Millennial, and which makes up a large share of the chain’s captured market. These shifts could indicate that both brands reclaimed some younger traffic toward the end of the year.
At the same time, both brands saw broader audience diversification within their captured markets. Sweetgreen increased its share of “Wealthy Suburban Families”, while CAVA saw gains among “Upper Suburban Diverse Families” and “Near-Urban Diverse Families”. This suggests that growth among older and more financially stable segments is likely helping to offset some of the pullback from younger diners.
And while some of CAVA and sweetgreen’s suburban and near-urban audience gains likely reflect both chains’ continued unit expansion beyond urban cores, the rise in young urban traffic indicates that strategic initiatives are resonating with traditional audiences. Menu innovation and tools that give diners greater control over nutritional inputs – particularly offerings aligned with protein-forward trends – may be helping to re-engage young urban diners.
Why Focused Strategy Matters More Than Ever in Fast Casual
As consumer budgets remain under pressure, CAVA and sweetgreen illustrate that sustaining momentum in today’s dining landscape requires a deliberate, multi-pronged strategy. Thoughtful real estate decisions can expand a brand’s consumer base while innovation and loyalty programs keep existing audiences engaged.
The broader industry takeaway is clear: brands that deepen relevance across multiple consumer segments may be best positioned to compete for share-of-stomach in the months ahead.
Which restaurant brands will succeed in 2026? Visit Placer.ai/anchor to find out.
Placer.ai leverages a panel of tens of millions of devices and utilizes machine learning to make estimations for visits to locations across the US. The data is trusted by thousands of industry leaders who leverage Placer.ai for insights into foot traffic, demographic breakdowns, retail sale predictions, migration trends, site selection, and more.
Year-over-year (YoY) visit performance for RBI chains was mixed in Q4 2025. Burger King (0.7%) and Popeyes (-0.5%) had nearly flat foot traffic, while Firehouse Subs (3.9%) had more significant growth. Meanwhile, Tim Hortons (-4.5%) experienced a significant visit gap.
Diving Into Each Brand
Foot traffic trends across RBI brands in Q4 2025 reveal a divide in chain performance. Burger King and Firehouse Subs were the primary drivers of domestic visit growth, while Popeyes and Tim Hortons experienced softer traffic patterns.
As the monthly visit graph below shows, Burger King’s Q4 2025 momentum came mostly in December 2025, coinciding with the brand’s limited-time SpongeBob Movie Menu and its 13 Days of Deals promotion. Meanwhile, Firehouse Subs sustained visit growth throughout Q4 2025, supported by continued expansion of its store footprint.
Popeyes visits and same-store visits tracked closely and remained largely flat in Q4 2025, pointing to continued challenges for the brand. RBI has emphasized long-term operational improvements and a renewed focus on core menu items as key levers for improving Popeyes’ performance, and while the impact of these initiatives has yet to materialize in the visit data, they could begin to support meaningful growth in 2026.
Domestic traffic to Tim Hortons – a relatively small chain in the U.S. coffee space – lagged significantly in Q4 2025. However, RBI has signaled ambitions to replicate the brand’s international success domestically, leveraging a robust promotional calendar and an accelerated expansion strategy that could help lift brand awareness and strengthen consumer loyalty over time.
What’s next for these brands in 2026? Visit Placer.ai/anchor to find out.
Placer.ai leverages a panel of tens of millions of devices and utilizes machine learning to make estimations for visits to locations across the US. The data is trusted by thousands of industry leaders who leverage Placer.ai for insights into foot traffic, demographic breakdowns, retail sale predictions, migration trends, site selection, and more.
Our recent analysis highlighted Dutch Bros’ push to capture a greater share of morning-daypart visits alongside its aggressive expansion strategy. Now, we’ll dive deeper into the connection between these two aspects of Dutch Bros’ strategy. Using an AI-powered analysis of visitor behavior we’ll explore how Dutch Bros’ play for the morning commuter could help foster brand recognition and loyalty in new markets, driving success as the chain grows its footprint.
Expansion Sets the Stage For Growth
Dutch Bros saw consistently positive visit growth in 2025, largely driven by rapid unit expansion, while the chain’s elevated same-store visits indicate strong demand as it entered new markets. The brand’s particularly robust end-of-year momentum may also be linked to its holiday season promotions.
Could Breakfast Drive Success in New Markets?
As Dutch Bros grows its footprint, its visitor’s journeys appear consistent with a brand yet to cement itself as part of morning coffee and breakfast routines in new geographies.
In 2025, fewer Dutch Bros visitors came from home immediately before visiting the chain or continued to work immediately after visiting, compared to 2024. This shift may reflect consumers who are encountering the chain more organically as it opens in their area – with curiosity and novelty fueling irregular visits rather than visitation being part of an established routine or commute.
Perhaps morning commuters, the kind Dutch Bros hopes to attract with its aforementioned breakfast strategy, could be the key to turning discovery into loyalty among consumers in new markets.
Viewed together, two facets of Dutch Bros’ growth plan – expansion and morning commuter visits – appear highly complementary; expanded breakfast offerings could potentially facilitate the transition from unfamiliar brand to habitual pit stop as the chain grows its footprint.
What will Dutch Bros’ visit patterns reveal about its growth in the months ahead? Visit Placer.ai/anchor to find out.
Placer.ai leverages a panel of tens of millions of devices and utilizes machine learning to make estimations for visits to locations across the US. The data is trusted by thousands of industry leaders who leverage Placer.ai for insights into foot traffic, demographic breakdowns, retail sale predictions, migration trends, site selection, and more.
Economic pressures created a challenging backdrop for the QSR space in 2025. Many consumers adjusted their dining-out habits, leading to uneven foot traffic across the category. Within this environment, AI-powered location intelligence suggests that Yum! Brands – the parent company of Taco Bell, KFC, Pizza Hut, and Habit Burger & Grill – has been comparatively well positioned. We dove into the data for a closer look at how Yum! and its portfolio performed in 2025 and the most recent Q4.
Yum! Brands in the Driver’s Seat
Although limited-service restaurants faced headwinds in 2025, Yum! Brands appeared to stay ahead of the pack. As a whole, the company's portfolio – QSRs plus the smaller Habit Burger & Grill – posted year-over-year (YoY) foot traffic growth in every quarter, outperforming the broader QSR category, which recorded YoY visit declines during much of the year.
Beyond value and compelling menu innovation, convenience and ease of experience remain central to why consumers choose limited-service chains. To reinforce its advantage, Yum! has spent the past year expanding its suite of AI-driven technology tools across its brands – platforms designed to optimize restaurant operations, delivery, and digital ordering. The company has even pointed to its proprietary software as an enabler of daily menu drops and viral promotions, reinforcing the other two critical motivations for limited-service diners: craveability and value. As these tools roll out to more locations, the data suggests Yum!’s competitive edge could continue.
How Are Yum!’s Brands Performing?
An analysis of foot traffic across Yum! Brands’ portfolio highlights which concepts are driving the company’s visit gains. Pizza Hut and Habit Burger & Grill recorded YoY monthly overall visit and same-store visit growth in most of Q4 2025 – indicating that underlying demand remains intact despite heightened volatility in the current economic environment.
Of the four brands, however, Taco Bell remains Yum!’s primary driver of growth. The brand delivered the largest and most consistent YoY monthly overall visit and same-store visit growth throughout Q4 2025 – with National Taco Day promotions and the return of Cheesy Dipping Burritos likely contributing to elevated traffic.
Meanwhile, KFC experienced month-to-month visit gaps throughout Q4 2025 while mustering nearly flat same-store visits. This could suggest that while the brand has consolidated its footprint, existing locations see sufficient demand to support a broader turnaround strategy.
Yum! What’s Next?
Even as economic pressures continue to reshape how consumers engage with limited-service dining, Yum! Brands appears well positioned to navigate ongoing uncertainty. A combination of operational investment and consumer-facing innovation suggests the company’s portfolio has built a durable foundation to support evolving market conditions.
Want more restaurant industry insights? Visit Placer.ai/anchor.
Placer.ai leverages a panel of tens of millions of devices and utilizes machine learning to make estimations for visits to locations across the US. The data is trusted by thousands of industry leaders who leverage Placer.ai for insights into foot traffic, demographic breakdowns, retail sale predictions, migration trends, site selection, and more.
Tractor Supply’s growing footprint continues to stand out in a retail environment where many chains remain cautious about physical expansion. We took a closer look at Tractor Supply’s market positioning to better understand how the chain’s deliberate expansion strategy sets it up for success in 2026.
Tractor Supply’s Expanding Footprint
Tractor Supply continued to scale its physical footprint in 2025, leveraging the acquisition of former Big Lots sites and reinforcing store growth as a core lever of its “Life Out Here” strategy. The chain’s expansion likely contributed to its steady year-over-year (YoY) visit growth throughout 2025. Meanwhile, positive average visits per location in most months suggests that new stores were capturing incremental demand rather than diluting traffic at existing locations – reinforcing management’s commentary around limited cannibalization.
Tractor Supply intends to open around 100 new stores in 2026 as part of its longer-term roadmap to 3200 stores (the retailer currently has 2,398 locations), setting high expectations for continued foot traffic growth in 2026.
Tractor Supply Meets Demand Where Supply Is Limited
As Tractor Supply expands, its strategy has been focused on rural and western high-growth markets where demand remains underserved. And with a relatively small store format, Tractor Supply has a distinct advantage over big-box chains that often face site-selection challenges in these markets.
Analysis of AI-based potential market data combined with the STI: Market Outlook dataset shows that the unmet demand (demand minus supply) for building materials and supplies within Tractor Supply’s potential market – i.e. the areas from which it drives traffic – far surpasses unmet demand in the wider Home Improvement category’s potential market. This comparison – in just one of the retail categories that Tractor Supply occupies along with its peers – suggests substantial white space for the chain, driven by a footprint that prioritizes underserved markets rather than the more established ones where many industry counterparts compete.
And as Tractor Supply expanded between 2024 and 2025, unmet demand for building materials and supplies in the chain's potential market increased, even as unmet demand across the broader Home Improvement category declined. Together, these trends point to a site selection strategy that places Tractor Supply in high-demand regions where few retailers are positioned to fully meet consumer needs.
Lessons for Retailers
What can we learn from Tractor Supply’s strategy and 2025 performance? Sometimes, it pays to be smaller, and unlock demand away from the competitive landscapes where bigger players operate. By pairing an accelerated store-opening strategy with purposeful site selection, Tractor Supply appears well-positioned for sustained traffic growth.
Will Tractor Supply continue to build momentum in 2026? Visit Placer.ai/anchor to find out.
Placer.ai leverages a panel of tens of millions of devices and utilizes machine learning to make estimations for visits to locations across the US. The data is trusted by thousands of industry leaders who leverage Placer.ai for insights into foot traffic, demographic breakdowns, retail sale predictions, migration trends, site selection, and more.
Columbus, Ohio is among the Midwest’s fastest-growing metro areas. Like downtown business districts across the country, its urban core is seeing a return to the office. What do inbound commuter traffic patterns reveal about this shift – and how can local stakeholders, from retailers to commercial real estate investors, capitalize on the opportunities created by this growing influx?
Downtown Columbus’s Growing Commuter Visits
Growing metro areas depend on vibrant downtown anchors for employment and economic activity. In Columbus, OH, the downtown area has long served as a key destination for commuters as the city’s population and labor force have grown. Favorable business incentives, and the presence of major employers such as Nationwide Insurance, Huntington Bancshares, and American Electric Power contribute to Downtown Columbus’s rising commuter population.
Urban and Suburban Commuter Lifestyles
Analysis of the regions with the highest shares of commuters to Downtown Columbus shows that both nearby urban neighborhoods and surrounding suburbs contribute significantly to the city’s downtown workforce.
The map below reveals that over the past 12 months, the densely-populated 43201 zip code drove one of the highest shares of downtown commuters. This urban corridor includes the rejuvenated Weinland Park neighborhood and parts of the University District and trendy Short North. Many of these commuters are likely students or recent graduates entering the workforce – drawn downtown by internships, early-career roles, and professional opportunities.
At the same time, the suburbs also play a defining role in Downtown Columbus’s workforce composition. The 43123 zip code – centered around Grove City – and 43026 – anchored by Hilliard – also had relatively large shares of Downtown Columbus commuters. This reflects a broader trend of workers balancing suburban lifestyles with city-based employment opportunities.
Downtown Demographics
While Downtown Columbus’s workforce reflects a mix of suburban and urban commuters, the composition within its commercial corridors is even more nuanced – shaped by distinct demographic and psychographic characteristics.
Among the analyzed corridors, the Arena District stood out for having the highest median household income (HHI) and the largest share of the “Young Professionals” segment among commuters in 2025, suggesting a workforce anchored in early- to mid-career white-collar roles. This profile aligns with the district’s mix of corporate offices, and sports and entertainment–adjacent employers that may attract younger, upwardly mobile workers.
The Discovery District followed closely in terms of median income, but its psychographic mix skewed differently. The area had one of the highest shares of the “Ultra Wealthy Families” segment, alongside the largest concentration of the “City Hopefuls” segment, among the downtown corridors analyzed. Anchored by institutions such as Columbus State Community College, major healthcare employers, research organizations, and cultural assets like the Columbus Metropolitan Library and the Columbus Museum of Art, the district appears to draw a diverse, but upper-income mix of commuters tied to public service, education, and nonprofit work.
The Uptown District stood apart with a median commuter HHI below that of the Columbus, OH DMA, and elevated shares of “City Hopefuls” and “Young Professionals” compared to the region. This profile likely reflects the district’s concentration of government offices and white-collar employers in law and finance, alongside the service-sector workforce that supports the area’s high daily activity – together pulling a wide spectrum of income levels into the corridor each day.
With the right strategy, the diversity among commuters – who are also consumers of restaurants, retailers, and other service-oriented industries – creates opportunities for businesses to engage their target audiences where they spend meaningful daytime hours.
A Downtown For All
A downtown reflects not only a metro’s economic strength but also the fabric of its cultures and communities. In Columbus, the downtown serves as both a hub of commercial activity and a crossroads for commuters from diverse backgrounds. This diversity presents businesses with opportunities to carve out a target audience and civic leaders with a responsibility to ensure that Downtown Columbus continues to serve the needs of all who power it.
For more regional analyses, visit Placer.ai/anchor.
Placer.ai leverages a panel of tens of millions of devices and utilizes machine learning to make estimations for visits to locations across the US. The data is trusted by thousands of industry leaders who leverage Placer.ai for insights into foot traffic, demographic breakdowns, retail sale predictions, migration trends, site selection, and more.
Digging Into Dining
The dining industry showcased its agility over the past couple of years as it rapidly adapted to shifts in consumer preference brought on by COVID and rising prices. And with a new year around the corner, the pace of change shows no signs of slowing down.
This white paper harnesses location analytics, including visitation patterns, demographic data, and psychographic insights, to explore the trends that will shape the dining space in 2024. Which dining segments are likely to pull ahead of the pack? How are chains responding to changes in visitor behavior? And where are brands driving dining foot traffic by taking advantage of a new advertising possibility? Read on to find out how dining leaders can tap into emerging trends to stay ahead of the competition in 2024.
Stepping Up To The Plate
Comparing quarterly visits in 2023 and 2022 highlights the impact of the ongoing economic headwinds on the dining industry. The year started off strong, with year-over-year (YoY) dining visits up overall in Q1 2023 – perhaps aided by the comparison to an Omicron-impacted muted Q1 2022. And while overall dining growth stalled in Q2 2023, several segments – including QSR, Fast Casual, and Coffee – continued posting YoY visit increases, likely bolstered by consumers trading down from pricier full-service concepts.
Foot traffic slowed significantly in Q3 2023 as inflation and tighter consumer budgets constrained discretionary spending. Overall dining visits fell 2.4% YoY, and full-service restaurants – with their relatively high price point compared to other dining segments – seemed to be particularly impacted by the wider economic outlook. But the data also revealed some bright spots: Fast Casual still succeeded in maintaining positive YoY visit numbers and Coffee saw its Q3 visit grow an impressive 5.4% YoY. As the return to office continues, a pre-work coffee run or lunchtime foray to a fast-casual chain may continue propelling the two segments forward.
Shifting Demographics and Shifting Dining Behavior
Restaurant visitation patterns have evolved over the past few years. Although an 8 PM seating was once the most coveted slot at fine-dining restaurants, recent visitation data suggests that sitting down to dinner earlier is rising in popularity.
But among the QSR segment, the opposite trend is emerging, with late-night visits rising. Analyzing hourly foot traffic to several major QSR chains reveals that the share of visits between 9 PM and 12 AM increased significantly between Q3 2019 and Q3 2023. Even Taco Bell – already known for its popularity among the late-night crowd – saw a substantial increase in late-night visits YoY – from 15.4% to 20.3%.
Younger Customers Staying Out Later
Who is driving the late night visit surge? One reason restaurants have been expanding their opening hours is to capture more Gen-Z diners, who tend to seek out nighttime dining options. But location intelligence reveals that younger millennials are also taking advantage of the later QSR closing times.
An analysis of the captured market for trade areas of top locations within one of Taco Bell’s major markets – the Chicago-Naperville-Elgin, IL-IN-WI Metropolitan area – reveals a year-over-four-year (Yo4Y) increase in “Singles & Starters.” The “Singles & Starters” segment is defined by Experian: Mosaic as young singles and starter families living in cities who are typically between 25 and 30 years old. As consumers continue to prioritize experiential entertainment and going out with friends, late-night dining may continue to see increased interest from young city-dwellers.
Smoothies Drive Weekend Visits
Millennials and Gen-Z consumers aren’t only heading to their favorite fast food joint for a late-night bite – these audience segments are also helping drive visits on the weekends. Smoothie King is one chain feeling the benefits of young, health-conscious consumers.
The chain, which opened in New Orleans, LA, in 1973 as a health food store, has since grown to over 1,100 locations nationwide and is currently expanding, focusing on the Dallas-Fort Worth CBSA. The area’s Smoothie King venues have seen strong visitation patterns, particularly on the weekends – weekend visits were up 3.4% YoY in Q3 2023. The smoothie brand’s trade areas in the greater Dallas region is also seeing a YoY increase in weekend visits from “Young Professionals” – defined by the Spatial.ai PersonaLive dataset as “well-educated young professionals starting their careers in white-collar or technical jobs.”
Sports and Dining - Match Made in Heaven
While some dining chains are appealing to the late-night or weekend crowd, others are driving visits by appealing to sports lovers. How have recent rule changes around student athletes changed the restaurant game, and how can college football teams drive business in their hometowns?
Scoring Big: Leveraging Fan Insights to Fuel Successful Partnerships
College sports have long been a major moneymaker, with top-tier teams raking in billions of dollars annually. And as of 2021, college athletes can enjoy a piece of the significant fan following of college sports thanks to the change in the NCAA’s Name, Image, and Likeness (NIL) rules, which now allows student athletes to sign endorsement deals.
Since then, multiple restaurants have jumped on the opportunity to partner with student athletes, some of whom have millions of followers on Instagram and TikTok. Chains like Chipotle, Sweetgreen, Slim Chickens, and Hooters have all signed college athletes to various brand deals.
How can brands ensure they partner with athletes their customers will want to engage with? Analyzing a chain’s audience by looking at the interests of residents in a given chain’s trade area can reveal which type of athlete will be the most attractive to each brand’s customer base. For example, data from Spatial.ai: Followgraph provides insight into the social media activity of consumers in a given trade area and can highlight desirable partnerships.
Examining the trade areas of Chipotle, Sweetgreen, Slim Chickens, and Hooters, for instance, reveals that Sweetgreen’s visitors tended to have the largest share of Women’s Soccer followers. Conversely, Sweetgreen’s trade area had lower-than-average shares of College Football Fans or College Basketball Fans, while residents of the trade areas of the other three chains showed greater-than-average interest in these sports. Leveraging location intelligence can help companies choose brand deals that their customers resonate with and find the ideal athletes to represent the chain.
College Gameday - Wins for Dining
Finding the right college athlete partnership is one way for dining brands to appeal to college sports enthusiasts. But dining chains and venues located near major college stadiums also benefit from the popularity of their local team by enjoying a major game day visit boost.
One of the country’s most popular college football teams, the Ohio State Buckeyes, can draw millions of TV viewers, and its stadium has a capacity of 102,780 – one of the largest stadiums in the country. And while tailgating is a popular activity for Buckeyes fans, nearby restaurants are some of the biggest beneficiaries of the college football craze. Panera experienced a 235.3% increase on game days as compared to a typical day, Domino’s Pizza visits grew by 283.3%, and Tommy’s Pizza, a local pie shop, saw its visits jump by a whopping 600.9%.
Game Day Visitor Spikes
This influx in diners also causes a major shift in game day visitor demographics, as revealed by changes in visitors at dining venues located near stadiums of two of the nation’s best college football teams – the Ohio State Buckeyes and Ole Miss Rebels. Based on Spatial.ai: Personalive data for the captured market of these dining venues, game day visitors tended to come from “Ultra Wealthy Families” when compared to visitors during a typical non-game day in September or October.
The analysis indicates that popular sporting events create a unique opportunity for restaurants near college stadiums to attract high-income customers game day after game day, year after year.
Subwars: Room for Everyone
While some spend game day tailgating or visiting a college restaurant, others hold a viewing party – with a six-foot submarine. And the sub’s popularity extends beyond Superbowl Sundays. Sandwich chains including Jersey Mike’s, Firehouse Subs, Jimmy John’s, and Subway (recently purchased by the same company that owns Jimmy John’s) have seen sustained YoY increases in visits and visits per venue in the first three quarters of 2023.
Some of the growth to these chains may be related to their affordability, a draw at all times but especially during a period marked by consumer uncertainty and rising food costs. And subway leaders seem to be seizing the moment and striking while the iron is hot – Jersey Mike’s opened 350 stores in 2023 and still saw its YoY visits per venue grow by 6.6%. And Subway reported ten consecutive quarters of positive sales, a promising sign for its new owner.
Sandwich Chains Attract a Wide Consumer Base
The love for a healthy, affordable sandwich extends across all income levels, with all four chains seeing a range in their visitors' median household income (HHI). Out of the four chains analyzed, Jersey Mike’s – which has long prioritized a suburban, middle-income customer – had the highest trade area median household income of the four chains at $77.3K/year. Subway, known for its affordability, had the lowest, with $62.9K/year. The variance in median HHI combined with the strong foot traffic growth shows that when it comes to sandwiches, there’s something for everyone.
So What’s The Dining Space Cooking Up?
Persistent inflation and declining consumer sentiment may pose serious challenges for the dining space, but emerging trends are helping boost some restaurants. Customers seeking out a late-night bite drive visits to QSR chains, and health-conscious diners are boosting foot traffic to smoothie bars and sandwich shops. Meanwhile, sports sponsorships and game-day restaurant visits can provide a boost to dining businesses that take advantage of these opportunities.

