

Ahead of the Pack in Retail and Dining
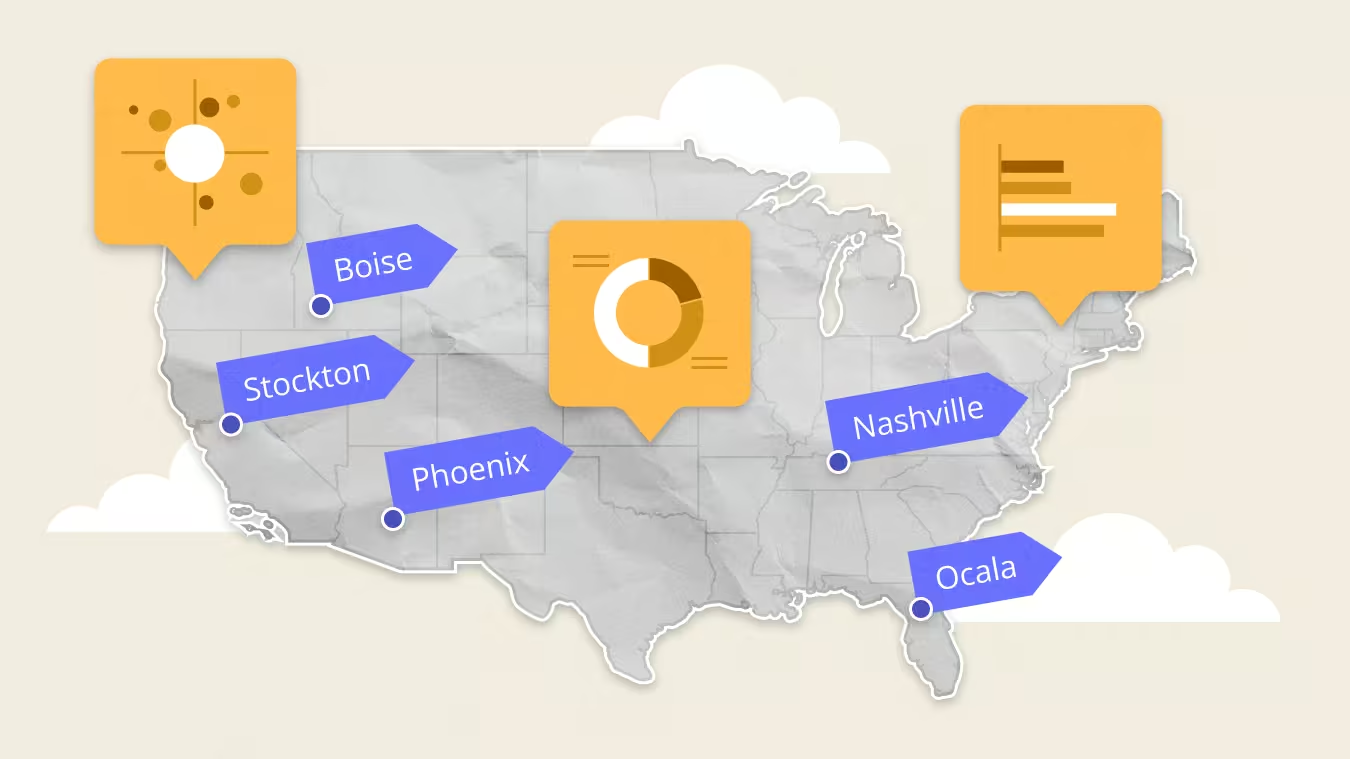
Our five metros for this year’s short list – Stockton (CA), Phoenix (AZ), Boise (ID), Nashville (TN), and Ocala (FL) – stand out for consumer momentum going into 2027. All five metro areas saw their populations increase by more than the average U.S. metro between 2024 and 2025, and their year-over-year (YoY) retail and dining traffic trends are outpacing the nationwide average.
Stockton, CA – A Bay Area Alternative Near the AI Boom
The Stockton-Lodi metro has long been home to Bay Area workers, many commuting over the Altamont Pass to the East Bay and Silicon Valley. And with tech employers like Nvidia expanding in Silicon Valley – and an AI boom supporting a regional return-to-office – Stockton could attract more households looking to pair Bay Area paychecks with a lower cost of living.
A Magnet for Professionals and Families
Stockton is already a natural landing spot for households looking for more space, affordability, and a slower pace outside the Bay Area’s largest cities. Audience segmentation for the trade areas of essential retailers – which nearly every household visits – offers a profile of the local consumer.
Between October 2025 and September 2026, households with children made up 29.0% of households in Stockton’s essential-retail trade areas, compared with 26.2% statewide. Educated Urbanites – high-earning, often single professionals – were also overrepresented, as were Flourishing Families (affluent, middle-aged families) and Singles and Starters (young singles and families starting out). With its mix of young professionals and established families, Stockton may be well suited to households working in the Bay Area – and could become an increasingly popular choice in 2027.
An Appetite for Limited-Service Dining
Data shows that Stockton’ work-from-home rates remain well below state and nationwide averages, and these busy, commuter-heavy households are also showing up in dining visitation trends.
Stockton posted the strongest overall dining visit growth of the five markets on this list, with limited-service chains leading the way. Fast-casual visits rose 5.2% YoY, double the statewide and nationwide growth rates. And even quick-service restaurants, which have faced significant headwinds in recent months, saw visits rise 1.5% YoY. That makes Stockton a market to prioritize for limited-service chains looking to reach young professionals and families.
Phoenix, AZ – Strong Retail Foundations
The Phoenix metro area has one of the nation’s fastest-growing populations, thanks in part to a strong job market. And one of the most significant regional employment catalysts is TSMC’s chip plant – poised to expand in 2027 – shaping real estate and retail demand.
Everyday Retail Segments Stand Out
As the Phoenix metro’s population climbs, so too does demand for essentials and lifestyle-forward retailers. YoY visits to several retail categories in the region beat out the nationwide benchmark over the last twelve months, including discount & dollar stores, clothing, and electronics stores. These trends point to a solid market for retailers looking to reach the region's growing households.
Shopping Center Hotspots
Phoenix’s growing population is also providing a visit lift to its shopping centers. Tempe Marketplace, Kierland Commons, Scottsdale Fashion Square, Chandler Fashion Center, and SanTan Village each posted consistent YoY visit growth over the past six months. As new households look for places that combine retail, dining, and entertainment, Phoenix’s shopping centers appear well positioned for continued growth in 2027.
Boise, ID – Inbound Households and Growing Demand
Boise, Idaho, is next in line for a chip-driven boom. Micron’s $50 billion complex, which will make memory chips for AI systems, is set to begin production in mid-2027. Construction has already generated thousands of jobs – with some 17,000 jobs statewide, including 2,000 at Micron, expected to follow as the plant comes online, making 2027 a pivotal year for the region.
Domestic Migration Is Ramping Up
Boise’s incoming tech boom coincides with accelerating household movement into the metro. Net domestic migration has added 2.8% to Boise’s population since September 2023, with half of that gain (1.4%) coming in the past year alone. And as Micron’s chip-related jobs come online, more households are likely to follow the trend.
Grocery Growth Signals Demand
A look at grocery visits nationwide and within the metro points to rising consumer demand in Boise. Visits to grocery chains across the metro rose 2.3% YoY over the past 12 months, outpacing the nationwide gain of 1.5%.
Expansion appears to be contributing to that growth, but demand is keeping pace: Average visits per location to Boise grocery stores also increased 0.7% YoY, slightly outpacing the national gain of 0.6%. For grocers considering Boise, the combination of an expanding population and rising traffic per location suggests room to grow as the metro heads into 2027.
Nashville, TN – Tourism Hits New Highs
Nashville’s steady population growth makes it an important retail market – and its landmark music venues and pilgrimage sites have also long made it a fixture on travel bucket lists. Just last year, the metro broke its own visitor spending record. And in 2027, a new NFL stadium could give the metro area an added boost.
Festivals Fuel Out-of-Market Visits
Over the past 12 months, visits to Nashville rose by 2.5%, likely driven in part by tentpole events like CMA Fest and Let Freedom Sing!, which spurred record crowds and an influx of consumer spending. An 8.4% YoY out-of-market visit surge in September coincided with Labor Day weekend trips and Americanafest – a citywide music festival.
Nashville Captures Overnight Stays
Analysis of overnight stays further highlights Nashville's strength as a top tourist destination. After all, multi-day trips provide greater consumer spending potential.
As the chart below shows, more than 80% of Nashville’s out-of-market visitors between September 2025 and August 2026 stayed overnight in the region, while just 4.7% visited for the day and spent the night elsewhere. And looking just at visit nights, only 3.0% were lost to other markets, meaning Nashville captures the vast majority of its visitors’ overnight stays. If these trends hold, the region may see another year of strong hotel demand in 2027.
Ocala, FL – The I-75 Boomtown
Rounding out our list of five markets to watch in 2027 is Ocala, FL – the fastest- growing metro in the country, where real estate development is helping accommodate a booming population.
In May 2026, Ocala’s city council approved 2,700 new residences and nearly a million square feet of commercial space, with more development on the horizon. The metro’s position between Miami, Atlanta, Tampa, and Jacksonville has also made it a logistics hub, home to several retail distribution centers.
Ocala Draws More Visits by Inbound Commuters
Inbound commuter visits to Ocala have risen in recent months, with YoY growth reaching 8.2% in September 2026.
A wave of new jobs is likely helping draw commuters to Ocala, which has posted the fastest job growth of the five markets on this list. Its I-75 logistics corridor keeps growing, with ECMD opening its first Florida distribution center there in September 2026. The World Equestrian Center added roughly 300 jobs with its new Equestrian Manor, while a steady construction pipeline is creating more employment opportunities. Meanwhile, improvements underway along I-75 are expected to expand capacity and improve access to local businesses.
Retail and Dining Chains Outperform in Ocala
That growing daytime population may also be showing up at the register. Ocala has attracted rapidly expanding chains like Raising Cane’s and 7 Brew Coffee, which made their market debuts in 2026 – and established chains in the metro continue to outperform statewide and/or nationwide visit benchmarks.
Here’s to 2027
Stockton, Phoenix, Boise, Nashville, and Ocala each approach 2027 on strong footing and with a growth story of their own – though only time will tell what the year has in store.
Visits Rise, Markets Diverge
The return-to-office debate sometimes feels like it’s stuck on repeat. Employers tighten attendance rules, workers push back – or look for loopholes – and around it goes.
But amid the noise, real progress is being made on the ground. In H1 2026, nationwide office visits grew 6.0% year over year (YoY) and the post-pandemic gap narrowed to its slimmest margin yet.
That national number, though, is an average of increasingly different stories. The same 6.0% contains a Miami sitting within striking distance of 2019, a San Francisco gaining momentum, and a Denver still trailing; a Dallas where roughly one in seven office visits happens on a Friday and a Chicago where it's barely one in ten; a New York where almost half of all visits now come from within five miles and a Houston where it's just a quarter.
This report examines office recovery trends across 11 major U.S. markets, exploring where attendance is gaining fastest, and how hybrid workweeks and commute patterns differ by city.
Back in Acceleration Mode
Key Insights From this Section:
- Nationwide office visits grew 6.0% YoY in H1 2026, narrowing the gap with H1 2019 to 31.2%.
In H1 2026, nationwide office visits grew 6.0% YoY, a marked acceleration from the 1.9% YoY increase recorded in H1 2025. Total visits remained 31.2% below H1 2019 levels – the narrowest H1 gap since the pandemic began, and a notable improvement from -35.1% in H1 2025.
Local Realities Shape Regional Markets
Key Insights From this Section:
- Macro trends masked significant divergence across markets.
- Sunbelt markets Miami, Dallas, and Atlanta – along with New York – remained closest to their pre-pandemic office visit levels.
- West Coast markets posted the fastest YoY growth, while slower markets such as Washington, D.C. and Denver continued to recover at a more gradual pace.
Sunbelt Leaders Ride a Corporate Relocation Wave.
Miami remained the nation's standout market in H1 2026, sitting closest to its 2019 baseline (-11.5%) while also continuing to post above-average YoY growth (+7.7%). Although the broader metro area lost population last year, the city itself is growing, and an ongoing wave of corporate relocations likely helped draw more workers into local offices.
Atlanta and Dallas also outpaced the nationwide recovery baseline, buoyed by their own steady stream of corporate moves. And though Dallas’ YoY growth came in slightly below the nationwide average at 5.4%, the Texas hub has less ground left to recover than most markets.
Finance-heavy New York Stays Ahead.
After Miami, New York (-15.8% vs. 2019) sat closest to its pre-pandemic baseline of any market tracked in H1 2026. Office visits in the city grew another 4.0% YoY – below the +6.0% national rate, but consistent with a market building on substantial earlier gains. New York’s advantage is supported by its concentration of finance firms, many of which were early adopters of strict return-to-office policies.
The West Coast Mounts a Late Surge.
Los Angeles and San Francisco lagged nationwide recovery rates vs. 2019 in H1 2026 – but the two cities posted the fastest year-over-year gains in the nation. For LA (+13.0% YoY), much of that momentum reflects recovery from a bruising H1 2025, when January's wildfires and June's downtown unrest likely weighed on office visits. In San Francisco (+10.9% YoY), an influx of artificial intelligence startups and venture capital has fueled downtown leasing activity, helping pull workers back into a market that remained 41.4% below 2019 levels in H1 2026.
Every Market Is Moving Forward.
All other markets analyzed – including Boston, Chicago, and Houston – also posted YoY growth in H1 2026, with Chicago outpacing the nationwide benchmark at 6.9% YoY. Even remote-friendly Denver, which ranked last in its recovery relative to 2019, recorded a 3.3% YoY increase. Washington, D.C., meanwhile, posted the nation’s slowest annual growth at 3.0% – perhaps due in part to a sluggish job market.
The Workweek Bends Locally
Key Insights From this Section:
- The nationwide office week remained concentrated around a midweek core, with Tuesday visits down just 19.3% compared to H1 2019.
- Friday office attendance varied considerably across markets.
The Hybrid Week Holds
Hybrid work was still the name of the game in H1 2026. Tuesday remained the busiest day of the week, sitting just 19.3% below 2019 levels. Wednesday (-24.2%) and Thursday (-28.7%) rounded out the mid-week core, while Monday (-34.7%) continued to lag and Friday remained down more than 50%.
And though every weekday’s post-pandemic gap narrowed in H1 2026, the gains were uneven. Tuesday saw the biggest YoY jumps, followed by Wednesday and Thursday, while Monday and Friday saw only modest increases.
Friday’s Fade Varies by Market
Here too, the precise contours of the hybrid week varied significantly by market.
In some cities, Friday attendance largely mirrored the broader recovery. Miami and Dallas, for example – both among the leading recovery markets – recorded the nation’s highest Friday visit shares, with Atlanta also posting above-average Friday attendance. By contrast, markets with deeper overall visit deficits relative to 2019, including Chicago, Boston, and San Francisco, had some of the lowest Friday shares.
In other markets, however, Friday attendance appears to have reflected distinctly local conditions. New York, for example, combined a strong overall recovery with a relatively soft Friday share of just 11.9% – perhaps as commuters sought to avoid long regional-rail journeys heading into the weekend.
Houston, by contrast, posted a lower Friday share than its overall recovery might suggest, likely due in part to the energy industry’s fondness for compressed “9/80” schedules that grant alternating Fridays off. That practice may also help explain why Houston’s Friday share was already relatively low in H1 2019.
The Power of Proximity
Key Insights From this Section:
- Visits originating within five miles of the office continued to recover fastest and posted the strongest YoY growth in H1 2026.
- Dense markets such as San Francisco, New York, and Chicago saw the greatest shift toward nearby visits, while sprawling Houston saw relatively little change.
Short Commutes Lead the Recovery
Nationwide, short commutes remained a key driver of the office recovery in H1 2026, extending a trend seen in earlier years. In H1 2026, these nearby visits also posted the fastest YoY growth – likely reflecting more frequent office attendance among employees with shorter, easier commutes.
Urban Density Drives Nearby Visits
Once again, however, the strength of this shift varied considerably by market. San Francisco led both in its share of close-by visits, at 48.1%, and in the growth of that share since H1 2019. The city's AI boom likely played a role here as well – the young startups driving the current leasing wave tend to favor in-person work and cluster in neighborhoods like Hayes Valley's "Cerebral Valley," where employees often live within walking distance of their desks.
Chicago (41.5%) and New York (45.3%) also ranked near the top. In these dense transit cities, urban-core residents account for a growing share of office traffic, while visits from suburban commuters remain more subdued. By contrast, the geography of office visits changed relatively little in sprawling, auto-centric Houston.
All News is Local
Halfway through 2026, the return-to-office push is still very much under way. New mandates keep coming into effect – a majority of Fortune 100 companies now require five days a week at a desk – and badge swipes have quietly become a performance metric.
But the national trend tells only part of the story. The pace and shape of the recovery still vary widely by market, reflecting differences in commuting patterns, urban form, industry mix, and local office policies. The next phase of the office recovery is therefore unlikely to follow a single national script – attendance may continue to rise broadly, but where it rises fastest will depend increasingly on the particulars of each market.

Explore how higher gas prices, the search for value, and nostalgia-driven demand shaped consumer traffic and behavior in H1 2026.
What Impacted Consumer Traffic in H1 2026?
The first half of 2026 put consumers to the test. Gas prices climbed sharply year over year, inflation picked back up, and economic uncertainty weighed on discretionary budgets. AI-powered location analytics show how visit patterns shifted in response, and which formats came out ahead.
1. Gas Hikes Test Consumer Resilience
Perhaps the biggest story of H1 2026 was the rapid rise in gas prices across the country. How did higher costs at the pump shape consumer traffic?
Rising Gas Costs Hit Dining Harder Than Retail
Through early 2026, retail and dining visits tracked closely. But as gas prices and inflation accelerated into the spring, the two diverged, with dining slipping into sustained declines while retail remained modestly positive.
Metro-level Trends Suggest Link Between Rising Gas Prices and Weaker Dining Demand
A closer look at metro-level dining traffic reinforces the connection between rising fuel costs and softer food-away-from-home demand. Analyzing the relationship between changes in gas prices across the 10 metro areas tracked by the EIA and the year-over-year (YoY) change in monthly restaurant visits reveals a clear pattern. Markets with the largest gas price increases generally experienced the weakest dining Miami was a notable exception, likely benefiting from strong tourism and seasonal migration.
Pain at the Pump Hit Long-Distance Destination Retail Hardest
Retail has proven more resilient than dining in H1 2026, but shoppers have not been indifferent to higher transportation costs. Even as overall retail traffic continued to grow through the first half of the year, consumers recalibrated their shopping trips – adjusting which outings they prioritized and how far they were willing to travel.
When gas prices first spiked in March, for example, discretionary retail visits fell YoY across distance bands, while non-discretionary traffic remained positive. But longer-distance discretionary trips took the hardest hit, while visits from less than 10 miles away saw just a modest YoY dip. Then, as the initial sticker shock began to fade in April, close-to-home visits led the discretionary rebound, while the 30+ mile band hovered near flat.
Non-discretionary retail visits, meanwhile, rose YoY across distance bands. But while short-distance trips overperformed for discretionary chains, they lagged for essentials. This suggests that consumers may have cut back on convenience-oriented runs and instead traveled farther for planned stock-up trips or lower-cost shopping destinations.
Higher Gas Prices Didn't Lead to More Consolidated Shopping Trips
One possible explanation for essential retail’s resilience – especially for longer-distance trips – is that consumers consolidated errands into fewer, longer shopping outings. But analyzing retail visitation patterns suggests that even if shoppers were combining more stops into a single trip, they appear to have spent less time in each individual store.
Comparing monthly average visit duration and monthly visit numbers for the Placer 100 Retail Index shows that average visit duration edged down even as overall retail visits remained above year-ago levels. This indicates that shoppers continued making trips but kept each store visit shorter and more targeted rather than lingering or browsing at length.
Consumers Adapted Rather Than Pulled Back
Higher gas prices reshaped consumer behavior without bringing retail activity to a halt. Rather than shopping less, consumers became more selective about where they traveled, what they prioritized, and which trips were worth the added cost.
2. Clear Value Proposition Continued to Drive Traffic
As consumers became more selective about which trips justified the added cost, they also became more deliberate in their pursuit of value. But in H1 2026, value did not always mean the cheapest option. Whether through discounted fuel, premium dining that felt worth the splurge, affordable treats, or well-timed promotions, the strongest-performing brands all gave consumers a compelling reason to spend.
Visit Gains For Retailers Selling Discounted Gas
Perhaps unsurprisingly, lower-priced gas proved a particularly powerful draw in H1 2026 as fuel costs rose – providing a clear tailwind for wholesale clubs, which typically offer cheaper fuel than traditional gas stations. Fuel centers at Costco, Sam's Club, and BJ's Wholesale Club posted strong YoY visit gains beginning in March 2026, when gas prices first spiked. And although growth moderated as prices eased, history suggests wholesale clubs are well positioned to convert at least some of these fuel-driven visits into longer-term customer relationships.
Clear Value Propositions Drove Traffic Growth
Other retail and dining segments also grew traffic despite the macroeconomic headwinds by delivering compelling value propositions. For off-price and thrift retailers, that meant meaningful savings relative to full-price competitors. Elsewhere, brands differentiated through experiences that justified the expense, as in fine dining, or through affordable indulgences that let consumers treat themselves without overspending.
Sales & Discounts Still Driving Visit Spikes
Even with discretionary budgets under pressure, promotions across retail and dining – from Bass Pro Shops' Father's Day Sale to Krispy Kreme's St. Patrick's Day giveaway – continued to generate meaningful traffic gains. This suggests that, despite shifting consumer behavior, promotions are still one of the most dependable traffic levers, with shoppers still willing to visit when brands offer a compelling reason to do so.
Value Came in Many Forms
H1 2026 showed that value extended well beyond low prices. Whether through discounted fuel, premium experiences, affordable indulgences, or compelling promotions, the brands that won were those that gave consumers a clear reason to spend.
3. Nostalgia Created Momentum for Brands Ready to Capitalize
Unlike value, which influenced traffic across much of retail and dining, nostalgia was a more targeted but highly effective traffic driver for brands positioned to capitalize on it. From viral social moments celebrating legacy restaurant formats to renewed interest in early-2000s mall brands, consumers gravitated toward familiar names and experiences. Brands that successfully tapped into that sentiment saw the payoff in their visit data.
Shopping Center Traffic Boost Coincided with Renewed Interest in Aughts Brands
The nostalgia wave appears to be lifting the venues where those heritage brands live. After starting 2025 in negative territory, quarterly visits to shopping centers improved steadily throughout the year and accelerated into 2026, with Q1 and Q2 each running more than 2% above prior-year levels – the strongest quarters in the period analyzed. The timing coincides with renewed consumer interest in aughts-era mall staples returning to the cultural spotlight, suggesting that Gen-Z's nostalgia for popular 90s and 2000s brands may be helping boost mall traffic.
Organic Social Buzz Fueled Traffic to Pizza Hut Classic Locations
Pizza Hut has spent the past several years preserving and restoring select legacy restaurants as official "Classic" locations, reviving iconic features like red roofs, Tiffany-style lamps, and checkered tablecloths to celebrate the brand's heritage. Yet despite the investment, these locations spent much of 2025 underperforming the broader chain. But fueled by organic social buzz celebrating their retro appeal – and reinforced by Pizza Hut's promotion of the Classic format – visits to these locations now significantly outpace the chain average.
With Yum! now selling Pizza Hut as part of a broader turnaround, the renewed appeal of these legacy restaurants suggests the brand's heritage could become one of its most distinctive competitive assets.
Barnes & Noble Is Gaining Even More Momentum
Barnes & Noble may have been the original heritage brand comeback story, and its continued strength in H1 2026 suggests the nostalgia wave has yet to reach its peak. Although the bookseller posted positive YoY visit growth in every month of the period analyzed, the pace picked up in 2026. Visits ran more than 13.0% above prior-year levels in the last three months of H1 2026 – an acceleration that is particularly notable given the already elevated 2025 baseline.
The chain's playbook – community-oriented stores, localized curation, and an experience built around browsing – shows that brick-and-mortar concepts once written off can not only stabilize but compound growth when the offering matches what consumers are seeking.
Nostalgia Still Has Room to Run
Nostalgia wasn't simply about looking backward – it rewarded brands that reintroduced familiar experiences in ways that resonated with today's consumers. The continued momentum behind Barnes & Noble suggests that trend may still have further to run.
The Traffic Playbook for a Selective Consumer
H1 2026 tested consumers with higher gas prices, renewed inflation, and persistent economic uncertainty – and consumers adapted their behavior accordingly. Visits shifted closer to home, dining bore more of the pullback than retail, and value became the clearest predictor of traffic growth. But H1 2026 also showed that consumers are still willing to show up for a compelling deal, a well-timed promotion, or a brand that taps into genuine cultural affection.
For retailers, restaurant operators, property owners, and investors alike, the winners of H1 2026 shared a common thread – a clear answer to the question "why is this trip worth it?" As macroeconomic pressures persist into the second half, that question - and the traffic data that answers it – will only grow more important.